The year-end checklist: from December to July
The year-end tasks from December preparation to the day of the second income tax instalment, on one page in calendar order: the count, reconciliation, bad debts, fixed assets, certifying the books, provisional tax on 17 February, the March and April returns, the general meeting. With a table that has separate columns for a sole proprietorship, a company and simplified taxation.
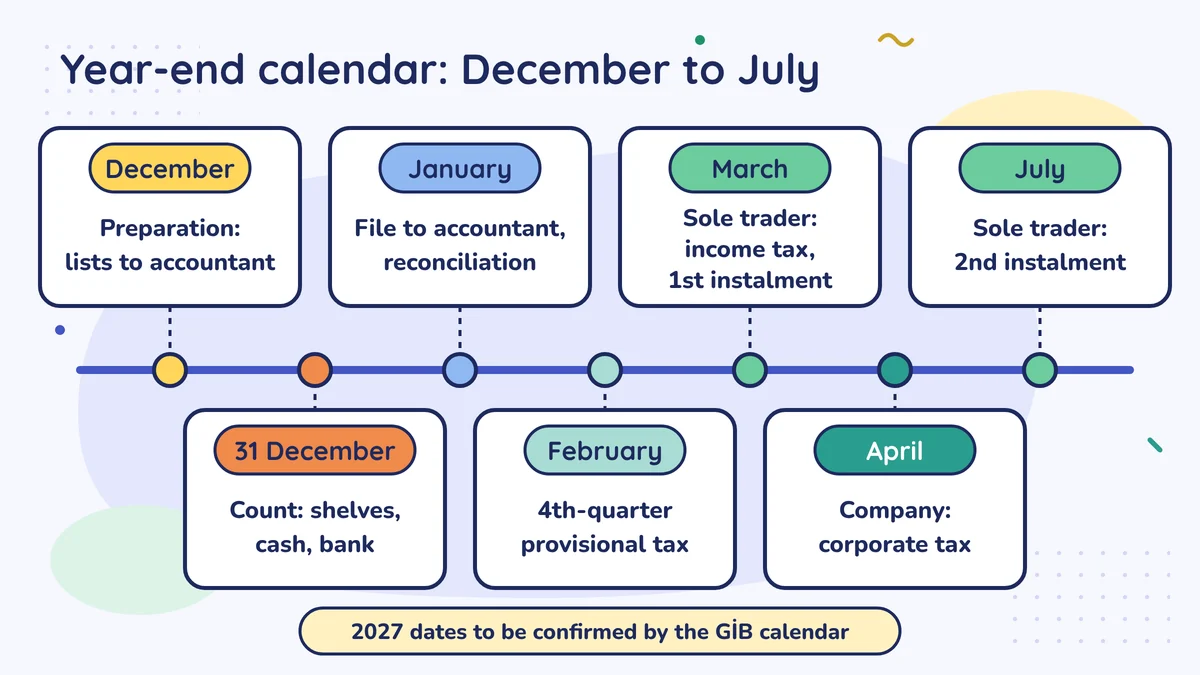
In December, prepare for the count and for the receivables and fixed asset (demirbaş) lists; on 31 December stock, cash and bank are counted; in the first week of January the file goes to your mali müşavir. The last provisional tax (geçici vergi) for 2026 is on 17 February 2027, a sole proprietorship's annual return and first instalment on 31 March 2027, a company's corporate tax on 30 April 2027, and the second instalment on 2 August 2027. The 2027 dates have been worked out from the rules; they become final when the GİB calendar is published. Under simplified taxation the list is short: Defter-Beyan records and documents.
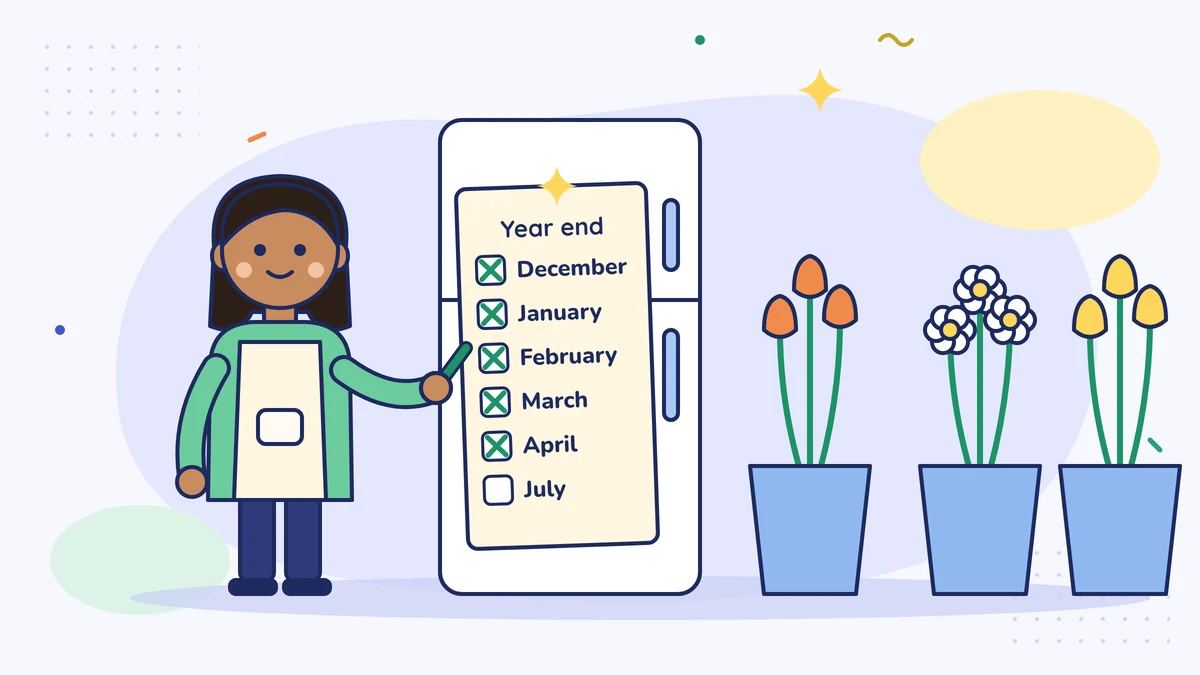
Zeynep Hanım the florist's fridge door
The rules described in this lesson are those of Turkish law.
The two busiest days of the year at Zeynep Hanım's flower shop are Valentine's Day and Mother's Day. She prepares for both weeks in advance: orders, vases, ribbons, extra staff. On the tax side, the busy months are December to April; but she never prepared for those. One day her mali müşavir (accountant) sent her a one-page list. Zeynep Hanım stuck the list on her fridge door and put a cross next to every job as it was done.
This lesson is that list. In the previous three lessons you saw each step in detail; here they are all in calendar order, on one page. Delete the lines that don't fit your situation.
December 2026: the preparation month
- The count day is set. An appointment on 31 December, the count list template ready (The December count).
- No invoices left unissued. The invoice for goods you delivered or work you finished in December is issued within 7 days at the latest (Invoice issuing period (in Turkish)). Also ask for the purchase invoices you are due to receive.
- The bad debt list is with your mali müşavir. Receivables in court or enforcement proceedings, and those unpaid despite a written request, with their documents.
- The fixed asset list is with your mali müşavir. Everything you bought, sold or threw away this year (The year-end file for your mali müşavir).
- If you are a company (or on the balance-sheet basis): opening certification of paper books. For a new book to be opened (such as the inventory book), the last day is 31 December 2026.
- Make year-end purchases for the business, not for tax. Buying something you don't need "to bring my tax down" is usually a loss. For a sole proprietorship, the income tax rate in 2026 is between 15% and 40%; an unnecessary 10,000 lira purchase reduces your tax by at most 4,000 lira, while 10,000 lira leaves your pocket. Also, a fixed asset above 12,000 lira (excluding VAT) does not become an expense in full this year; it is spread over the years.
Thursday 31 December 2026
- Count the shelves and sign the list.
- Count the cash box and write it in a signed record.
- Download the 31 December statement for every bank account, card and loan.
January 2027: the file goes to your mali müşavir
- First week: the count list, the cash count record, the statements and the loan balance letter are with your mali müşavir.
- First week: reconciliation messages have gone to customers and suppliers; collect the replies by the end of the month.
- December's regular returns as every month: muhtasar (withholding tax return) and the premium service declaration (prim hizmet) on 26 January, VAT on 28 January (A month's calendar).
- If you are a company (or on the balance-sheet basis): if you are continuing with your old book, the interim certification of the inventory book (and, in a company, the decision book) at a notary in January.
- If you are under simplified taxation: your October–December purchases and sales in the Defter-Beyan System by the end of January.
February 2027
- Wednesday 17 February: the last provisional tax for 2026 (October–December period). This period has existed again since 2025 (Law No. 7566). Not under simplified taxation.
- Ask your mali müşavir for an estimate of the annual return; set the money aside now for the March and April payments.
March 2027
- Wednesday 31 March: if you are a sole proprietorship, the annual income tax return and the first instalment.
- If you are a company (limited or joint-stock): the ordinary general meeting (olağan genel kurul) is held within three months after the end of the financial year (Turkish Commercial Code, Türk Ticaret Kanunu, art. 409 and 617). For a company using the calendar year, 31 March 2027.
April 2027
- Friday 30 April: if you are a company, the corporate tax return and the tax, in one go.
July 2027
- Second instalment: because 31 July falls on a Saturday, Monday 2 August 2027. Only for sole proprietorships; corporate tax has no instalments.
The 2027 dates in this list have been worked out from the rules; they become final when GİB's 2027 tax calendar is published, so check them once more then. Periods may be extended for public holidays or system problems; if there is an extension, GİB announces it.
Who does each job concern?
| Job | Sole proprietorship under real taxation | Company | Simplified taxation |
|---|---|---|---|
| Year-end count | Yes | Yes | Ask your mali müşavir |
| Account reconciliation | Yes | Yes | Recommended |
| Provision for doubtful receivables | If on the balance-sheet basis | Yes | None |
| Opening certification of books | On the balance-sheet basis, if you keep paper books | For paper books | Done in the system |
| 4th-period provisional tax | 17 February | 17 February | None |
| Annual return | Income tax, March | Corporate tax, April | None for this profit |
| General meeting | None | By the end of March | None |
The money side
The list is the paperwork side of the job. There is also a money side: provisional tax in February, the first instalment in March or corporate tax in April all fall in the same three months. In January Zeynep Hanım's mali müşavir gave her the estimated figures: 12,000 lira of provisional tax in February, a 20,000 lira first instalment in March, a 20,000 lira second instalment in July. From January on, Zeynep Hanım transferred money to her tax account every week. In mid-May the first provisional tax of 2027 also comes due; check the day in the GİB calendar. You saw how it is done in the lesson Setting money aside for tax.
At the end of April only one line on the list on the fridge door had no cross: the July instalment. The money for it was already waiting in the account.
Do this this week
Simplify the list in this lesson for your own situation: delete the lines that don't fit you, and enter the rest, with their dates, one by one into the calendar on your phone.
Common mistakes
- Making unnecessary purchases at year end to bring tax down. Because the tax rate does not exceed 40%, at least 60 kuruş of every lira spent comes out of your pocket; on top of that, a fixed asset above 12,000 lira (excluding VAT) does not become an expense in full that year.
- Thinking about the March, April and July payments in March. The provisional tax in February and the instalment in March come one after the other; start setting the money aside in January.
- Forgetting the general meeting in a company. The ordinary general meeting is held within three months after the end of the financial year; for a company using the calendar year, 31 March.
Sources
- GİB Tax Calendar
- Alomaliye: Return filing and payment periods
- İSMMMO: 2025 4th-period provisional tax (the fourth period under Law No. 7566)
- Turkish Commercial Code No. 6102 (Türk Ticaret Kanunu), art. 409 and 617 (ordinary general meeting) (mevzuat.gov.tr)
- Alomaliye: 2026 book certification dates
- Muhasebetr: 2026 thresholds and amounts (12,000 lira for VUK art. 313)
- KPMG: Taxpayers under simplified taxation and on the business-book basis keeping their records in the Defter-Beyan System (VUK General Communiqué No. 486, 486 Sıra No'lu VUK Genel Tebliği; records by the end of the following month)
Translated from the Turkish lesson. Last checked against Turkish rules: 12 October 2026. Not yet reviewed by a licensed accountant.
This is general information about Turkish rules, not financial, tax or legal advice. Rules change; check the date and the sources, and ask a licensed accountant (mali müşavir) about your own situation. Disclaimer