Profit share distribution: who decides, and how much withholding tax is deducted?
Ayten Hanım and Cengiz Bey's florist company closed last year with a profit; both want their share. Which profit the profit shares are distributed from and by what decision, the 15% withholding tax deducted in 2026, a worked example with figures, and the partner's own tax return.
In a limited company, profit shares are distributed only from net profit for the period and from reserves set aside for this purpose, by a decision of the general meeting of partners (ortaklar genel kurulu) (TTK art. 608 and 616). In 2026 the company deducts 15% income tax withholding from the profit share it distributes to a partner who is a natural person and pays it with the muhtasar return (Presidential Decision No. 9286). For the partner, half of the profit share is exempt from income tax; if the remaining half exceeds the limit, an annual return is filed.
A garden's harvest
The rules described in this lesson are those of Turkish law.
Ayten Hanım and her brother Cengiz Bey have a limited company: a florist's. The shares are half and half. The company closed 2025 with 400,000 lira of net profit after corporate tax. In April Cengiz Bey asked: "Half the profit is mine; when do we pay the 200,000 lira into my account?"
Think of a garden. The harvest comes in, but not all of it is eaten; some is kept as seed, some is sold, and the rest is shared. A company's profit is the same: first the tax on it is paid, the reserve the law requires is set aside, the partners decide how much to distribute, and withholding tax is deducted from the part distributed.
First, a reminder: profit shares (kâr payı) are specific to companies. In a sole proprietorship the profit already belongs to the owner; there is no distribution decision and no profit share withholding tax (Paying yourself a salary).
From which profit, and by whose decision?
- Source: Profit shares can be distributed only from net profit for the period and from reserves set aside for this purpose (Turkish Commercial Code art. 608). If the company is making a loss, or past years' losses have not been covered, there may be no profit to distribute.
- Reserves: No distribution decision can be taken until the reserves (yedek akçe) required by the law and the articles of association have been set aside (TTK art. 608). Your mali müşavir (accountant) calculates the rate and the limit.
- Decision: Distributing profit is a power of the general meeting of partners (general meeting for short; formerly called the partners' board) that cannot be delegated; unless the articles of association say otherwise, an absolute majority of the votes represented at the meeting is enough (TTK art. 616 and 620). The decision is usually taken when the year-end accounts are approved, that is, at the ordinary general meeting.
- Ratio: If the articles of association contain no other rule, profit shares are divided according to the nominal (stated) value of the partners' capital shares (TTK art. 608).
The partners do not have to distribute all of the profit. Profit left in the company stays there as "retained earnings" (geçmiş yıllar kârı); it is used to grow the business or can be added to capital (Putting in capital and capital increase).
Withholding tax in 2026: 15%
When a company distributes a profit share to a partner who is a natural person, it deducts income tax from that amount; this is called profit share withholding tax (kâr payı stopajı). For profit shares distributed since 22 December 2024 the rate is 15% (Income Tax Law art. 94/6-b-i; Presidential Decision No. 9286, Official Gazette 22.12.2024). The previous rate was 10%. If the partner is a company established in Turkey (a fully liable corporation), this withholding tax is not deducted; this lesson is about partners who are natural persons. The rate can be changed by Presidential decision; before a distribution, have your mali müşavir confirm the current rate.
The withholding tax arises when the profit share is paid to the partner or credited to the partner's account. In practice, once the distribution decision is taken and the amount is credited to the partner's account, the withholding tax goes into that month's muhtasar return; paying the money months later does not postpone the withholding tax. The company reports and pays the amount it has deducted with the muhtasar return (Withholding tax and the muhtasar return).
Ayten Hanım and Cengiz Bey in figures
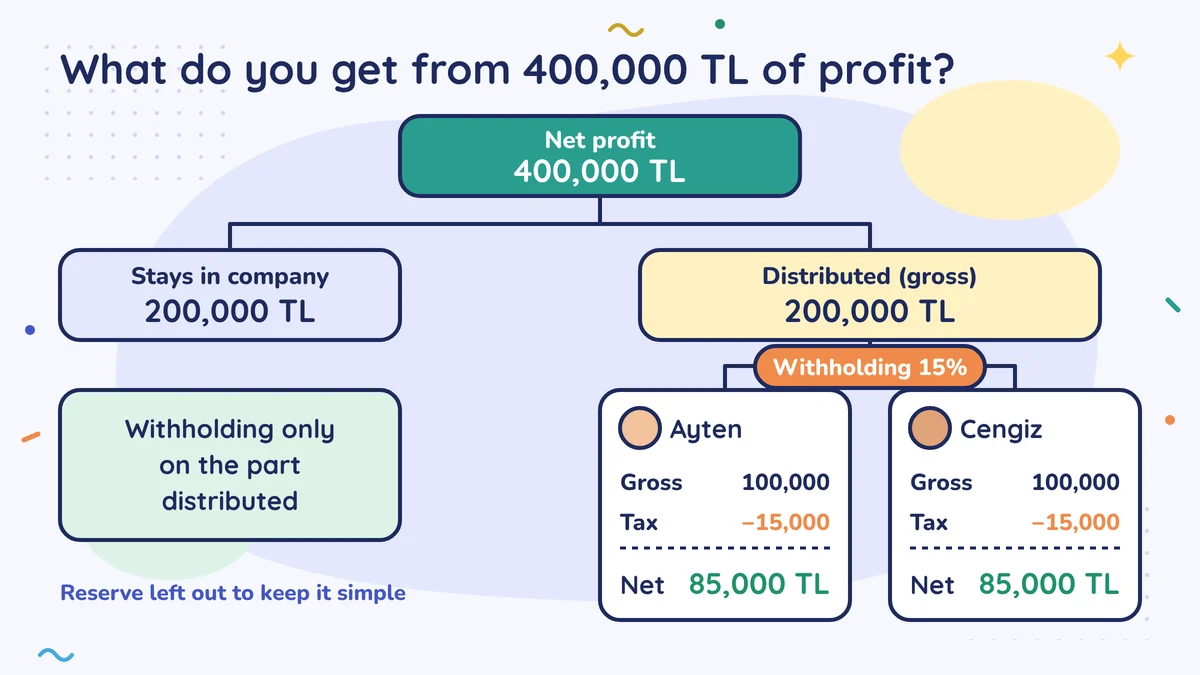
The general meeting decided to distribute half the profit and leave half in the company. To keep it easy to see, we have left the reserve out; in reality it is set aside first.
| Item | Total | Ayten Hanım | Cengiz Bey |
|---|---|---|---|
| Profit share to be distributed (gross) | 200,000 | 100,000 | 100,000 |
| Withholding tax (15%) | 30,000 | 15,000 | 15,000 |
| What the partner receives (net) | 170,000 | 85,000 | 85,000 |
| Profit left in the company | 200,000 |
Cengiz Bey receives not the 200,000 lira he expected, but 85,000 lira. Because half the profit was not distributed, and withholding tax was deducted from the part that was.
The partner's own tax return
A partner who is a natural person keeps half of the profit share received from a company in Turkey exempt from income tax (Income Tax Law art. 22/2). For the remaining half, that is, the taxable part of the gross amount of the profit share, you check whether it exceeds the upper limit of the second bracket of the annual income tax tariff (Income Tax Law art. 86/1-c). In the 2026 tariff this limit is 400,000 lira; the limit is checked against the total of the taxable halves of all profit shares you receive that year, and some other income on which withholding tax has been deducted (for example, workplace rent) also goes into this total.
Cengiz Bey's profit share is 100,000 lira gross. Half of it, 50,000 lira, is exempt. Since the remaining 50,000 lira does not exceed 400,000 lira, Cengiz Bey does not file an annual return for this profit share; the tax is completed by the withholding tax the company deducted. If the limit is exceeded, the profit share is declared and the withholding tax deducted by the company is set off against the tax calculated. If you have other income, have your mali müşavir do the calculation.
Look at the cash
A profit share decision creates a debt: the company must pay the money to the partner and pay the withholding tax with the muhtasar return. The profit may exist on paper but not in the cash box; the money may be waiting in receivables or in stock (Profit but no cash). Before the distribution decision, look at the company's cash plan (The 13-week cash plan).
If a partner took money out of the company during the year and it sits on the receivables from partners line, the profit share distributed can be set against this receivable (this is called offsetting, mahsup: deducting a mutual debt and receivable from each other); withholding tax is still deducted. We cover this in the lesson A partner taking money out of the company.
If the partners disagree
One partner may want the profit distributed, the other may want it left in the company. As a rule, the decision is taken by majority. But if the majority distributes no profit at all for years without a just cause, the other partner may be able to take legal action. The easiest way to prevent this dispute is to write the profit distribution principle into a partners' agreement from the start: for example, "every year at least half the profit is distributed, as far as the company's cash allows".
Ask your mali müşavir
- "How much profit can we distribute this year, and how much legal reserve must be set aside?"
- "Which month's muhtasar return will the withholding tax go into?"
- "Together with my other income, do I need to file an annual return?"
In one sentence
Profit shares are distributed by a general meeting decision, only from after-tax profit; in 2026, 15% withholding tax is deducted from profit shares paid to a partner who is a natural person, and half of the profit share is exempt on the partner's own return.
Do this this week
On your latest balance sheet, find the 'net profit for the period' and 'retained earnings' lines. If you are thinking of distributing profit this year, take the two figures to your mali müşavir and ask: 'How much can we distribute, how much will the withholding tax be, and does the company have enough cash?'
Common mistakes
- Thinking all of the profit can be distributed. First the tax is paid and the legal reserve is set aside; if there are past losses, there may be no profit left to distribute.
- Forgetting the withholding tax. In 2026, 15% is deducted from a profit share paid to a partner who is a natural person and paid with the muhtasar return; the partner does not receive the gross amount.
- Taking the decision without looking at the cash. The profit may exist on paper but not in the cash box; a distribution decision creates a payment debt for the company.
Sources
- KPMG Vergi: profit share withholding tax rate raised to 15% by Presidential Decision No. 9286 (9286 sayılı Cumhurbaşkanı Kararı) (Official Gazette 22.12.2024 / 32760)
- GİB: announcement on Presidential Decision No. 9286 (Lexpera copy)
- Dr. A. Bumin Doğrusöz, taxation of profit shares: half exempt, calculating the return limit (Ekonomi Gazetesi)
- PwC Tax Bulletin 2026/02: 2026 income tax tariff (upper limit of the second bracket 400,000 TL)
- Fatih Aras: Income Tax Law art. 86/1-c, the return limit for income from movable and immovable capital on which withholding tax has been deducted
- Ahmet Solmaz, profit distribution in a limited company: TTK art. 608, 616, 620 (MuhasebeTR)
- Income Tax Law No. 193 (193 sayılı Gelir Vergisi Kanunu), art. 22/2, 86/1-c and 94/6-b-i (mevzuat.gov.tr)
- Turkish Commercial Code No. 6102 (6102 sayılı Türk Ticaret Kanunu), art. 608 (mevzuat.gov.tr)
Translated from the Turkish lesson. Last checked against Turkish rules: 12 October 2026. Not yet reviewed by a licensed accountant.
This is general information about Turkish rules, not financial, tax or legal advice. Rules change; check the date and the sources, and ask a licensed accountant (mali müşavir) about your own situation. Disclaimer