The first payroll (bordro): from gross to net, step by step
On the first payroll you see a big figure at the top and a smaller one at the bottom. Every line in between has a name and an order. In this lesson we go from gross to net step by step with 2026 figures, and look at what you should check as the employer.
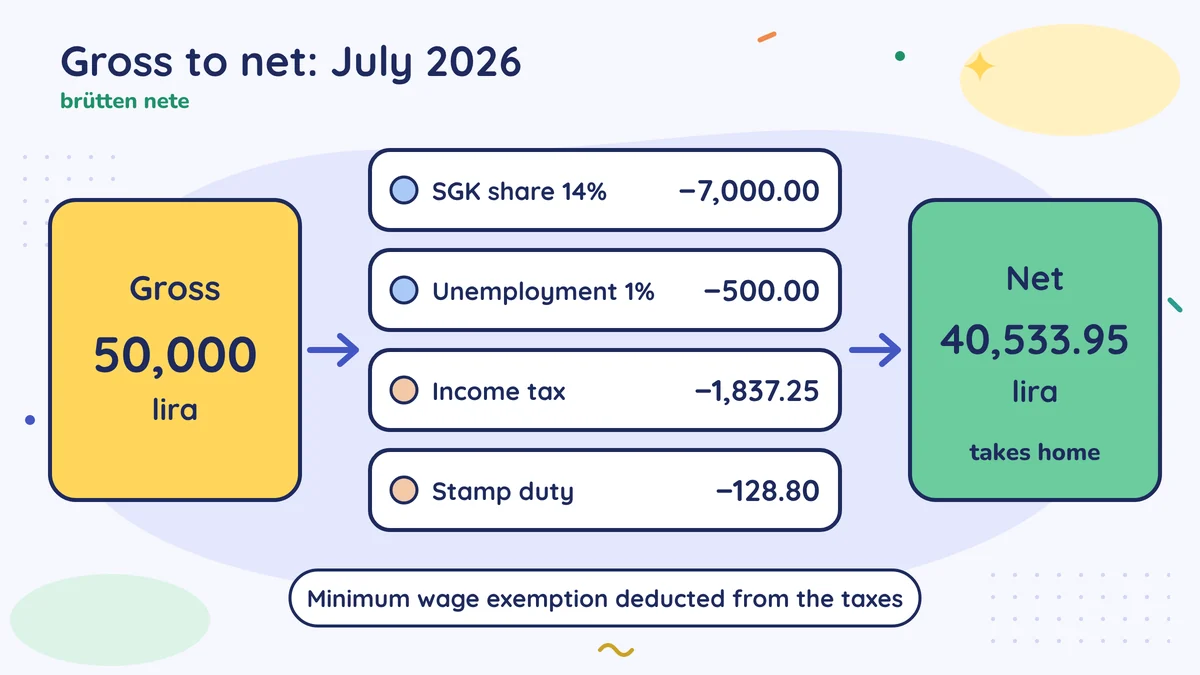
From the gross wage, the SGK employee share (14%) and the unemployment insurance employee share (1%) are deducted first; if there is no other deduction, the remaining amount is the amount income tax is calculated on (the tax base, matrah). The tax tariff is applied to this tax base, and an exemption equal to the tax a minimum wage employee would pay that month is deducted. Stamp duty is calculated on the gross and reduced by the part that falls on the minimum wage. For a tradesman taxed under simplified taxation (basit usul), no income tax is withheld from the wage, and the calculation changes. Your mali müşavir (accountant) prepares the payroll; you check the number of days, the gross and the net that will go to the bank.
Nermin Hanım the pastry-shop owner's first payroll
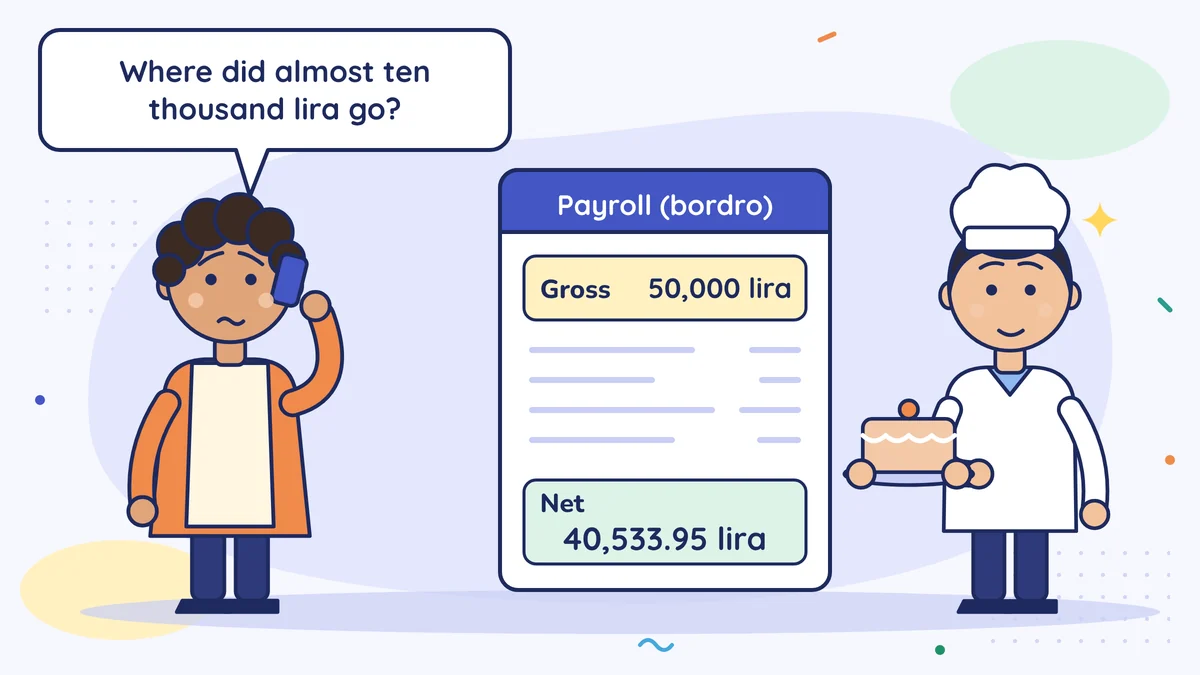
On the first day of July 2026, Nermin Hanım took on a pastry chef at her pastry shop: Burak Usta. The contract said the gross wage was 50,000 lira. In the first days of August, the payroll came from her mali müşavir (accountant). The figure at the bottom was 40,533.95 lira. Nermin Hanım called straight away: "Where did almost ten thousand lira go?"
The mali müşavir answered calmly: "None of it got lost. Each one is on a separate line, and each one has its order."
A payroll is read like a recipe
In a cake recipe, the ingredients go in in order: first the eggs and sugar, then the flour. If you change the order, the cake won't rise. In the payroll, too, the deductions are calculated in order, and each step uses the result of the one before. The payroll (bordro), that is, the monthly list where the wage, deductions and premiums are calculated, sets out this order.
Let's explain two words from the start:
- Gross (brüt): The wage in the contract, before deductions.
- Tax base (matrah): The amount the tax is calculated on.
Step by step: gross 50,000 lira, July 2026
It is Burak Usta's first month at this workplace. This calculation is for an employer who keeps books on the business-account basis (işletme hesabı esası) or the balance-sheet basis (bilanço esası); it is the same whether it is a sole proprietorship or a company. If you are a tradesman taxed under simplified taxation (basit usul), the return is still given, but no income tax is withheld from the wage; ask your mali müşavir which lines will be on your payroll. With 2026 figures:
| Step | Calculation | Amount (lira) |
|---|---|---|
| 1. Gross wage | 50,000.00 | |
| 2. SGK employee share | 14% | -7,000.00 |
| 3. Unemployment insurance employee share | 1% | -500.00 |
| 4. Income tax base | 50,000 − 7,000 − 500 | 42,500.00 |
| 5. Calculated income tax | 42,500 × 15% | 6,375.00 |
| 6. Minimum wage exemption (July 2026) | -4,537.75 | |
| 7. Income tax to withhold | 6,375 − 4,537.75 | -1,837.25 |
| 8. Stamp duty | 50,000 × 7.59 per thousand = 379.50; exemption 250.70 | -128.80 |
| Net (what the employee takes home) | 40,533.95 |
A short explanation of the steps:
SGK and unemployment share (steps 2–3). These are the employee's own premiums. They are deducted from the wage and paid to SGK (Social Security Institution) through you.
Income tax (steps 4–5). In the 2026 wage tariff (General Communiqué on Income Tax No. 332), the first 190,000 lira of the tax base accumulated within a year is taxed at 15%. Because it was Burak Usta's first month at this workplace, the calculation was made at 15%.
Minimum wage exemption (step 6). The part of the wage equal to the minimum wage is exempt from tax, that is, no tax is taken from that part. For this, an amount equal to the tax a minimum wage employee would pay that month is deducted from the calculated tax. This amount was 4,211.33 lira in the first six months of 2026. From 1 July 2026 it became 4,537.75 lira (GİB's announcement dated 4 August 2026). If the employee receives wages from more than one employer, the exemption is applied only to the highest wage.
Stamp duty (step 8). It is 7.59 per thousand of the gross wage. The part that falls on the minimum wage (250.70 lira a month in 2026, that is, 33,030 × 7.59 per thousand) is exempt (Stamp Duty Law (Damga Vergisi Kanunu), attached Table No. 2, IV-34).
The same steps are followed for a minimum wage employee too. But the exemptions bring the tax to zero, and 28,075.50 lira net remains from 33,030 lira gross. That table is in the lesson What an employee really costs you. To try it with your own figure, you can use the gross-to-net calculator (in Turkish). If you promised the employee a net figure, find the gross with the net-to-gross calculator (in Turkish).
Same gross, same net every month?
Not always. Two things can make the net move from month to month:
- The tax base accumulates over the year. Once Burak Usta's total tax base at this workplace passes 190,000 lira, the part above it is taxed at 20%. With a tax base of 42,500 lira a month, this happens in the fifth month: the total of four months is 170,000 lira, and with the fifth month it is 212,500 lira. In the November payroll, the net drops a little. The wage hasn't gone down; the tax bracket has changed.
- The exemption amount changes during the year. The minimum wage employee's own accumulated tax base also passes 190,000 lira in July. That is why the exemption went up in July. From August, because the minimum wage employee's tax is calculated entirely at 20%, the exemption changes again. Your mali müşavir's payroll program shows that month's amount.
If the employee asks "Why was less paid in this month?", the answer is usually in these two items. Explaining it to the employee from the start prevents an argument later.
Your side: what leaves the till
At the bottom of the payroll, apart from the employee's net, there are two more amounts. You pay these too:
- To SGK: The employee's deduction (7,500 lira) and your employer share. Without incentives, the employer share is 23.75% of the gross, that is, 11,875 lira. The total of 19,375 lira is paid by the end of the following month. If you benefit from reductions the state makes to the employer share (incentives), the amount goes down; ask your mali müşavir which one fits your workplace.
- To the tax office: The income tax and stamp duty withheld, that is, 1,837.25 + 128.80 = 1,966.05 lira. It is paid together with the withholding and premium service return (muhtasar ve prim hizmet beyannamesi).
The details of the total cost can be seen in the employer cost calculator (in Turkish).
Your mali müşavir prepares the payroll, you check it
Your mali müşavir's program does the calculation. But you are the only one who knows the right information about the employee on the payroll. Ask these questions every month:
| Check | By looking at |
|---|---|
| Are the employee's name and identity number correct? | Personnel file |
| Is the number of days correct? Are leave, sick-report days and days they didn't come reflected? | Your timesheet |
| Is the gross wage the same as in the contract? | Employment contract |
| Has overtime or a bonus been entered? | Your records |
| Is the net amount the same as the amount you will send to the bank? | Bank instruction |
If a line is wrong, say so before the return is given. That is when correcting it is easiest. The number of days and the timesheet are the subject of the next lesson: Paying wages and the timesheet.
Nermin Hanım read the table line by line, and as she hung up she said: "So the ten thousand lira didn't vanish, it just goes out through other doors."
Do this this week
Enter your employee's gross wage from the contract into the gross-to-net calculator and note the net that comes out. When the first payroll comes, compare it with this figure. If there is a difference, ask your mali müşavir (accountant) why; usually the answer is in the number of days or the exemption amount.
Common mistakes
- Approving the payroll by looking only at the bottom figure. If the number of days and the gross wage are wrong, the net is wrong too. Look at these two first.
- Thinking the employee's deduction is your own cost. The SGK employee share and the tax are deducted from the employee's gross. Your extra cost is the employer share, but you pay all of it in.
- Saying the net will stay the same every month. Because the tax bracket and the exemption amount change during the year, the net can move from month to month with the same gross.
Sources
- SGK: The employer's obligations (deducting premiums and payment deadline) (İşverenin Yükümlülükleri)
- Income Tax Law (Gelir Vergisi Kanunu) art. 23/18 (minimum wage exemption) and art. 103 (tariff)
- PwC Social Security Announcement 2026/06: minimum wage exemption income tax amount of 4,537.75 lira from 1 July 2026 (GİB announcement)
- Alomaliye: GİB announcement, MUHSGK minimum wage exemption amount (4 August 2026)
- EY Circular 2026/1: 2026 income tax tariff (General Communiqué on Income Tax No. 332, Official Gazette 31.12.2025)
- KPMG: Minimum wage income tax and stamp duty exemption (Law No. 7349, General Communiqué on Income Tax No. 319)
- Cott: Legal deductions on the payroll for 2026 (secondary source)
- EY: 2026 minimum wage
- KPMG: SGK premium rates 2026
Translated from the Turkish lesson. Last checked against Turkish rules: 9 October 2026. Not yet reviewed by a licensed accountant.
This is general information about Turkish rules, not financial, tax or legal advice. Rules change; check the date and the sources, and ask a licensed accountant (mali müşavir) about your own situation. Disclaimer